Sylvest Featured Across Leading UK Media Platforms: What It Means for Deal Sourcers & Property Investors
Building a trusted name in the UK property sector takes more than creating a platform. It requires visibility, credibility and…
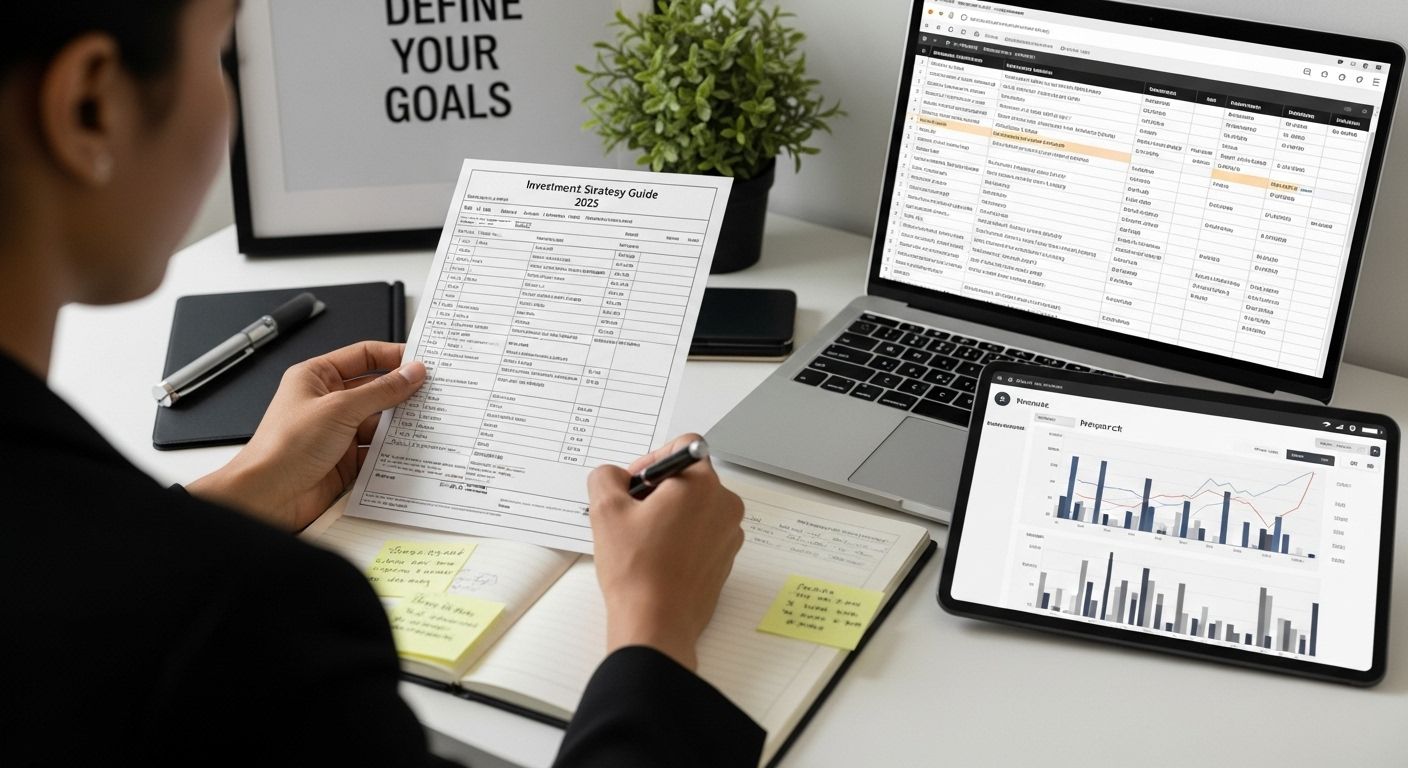
Building a successful property portfolio rarely happens by accident. The strongest investors begin with clear goals, understand their finances and choose an approach that matches their risk tolerance, available capital and timeframe. Property investment strategies provide a framework for making those decisions rather than simply buying properties and hoping they perform well.
Whether your goal is rental income, long-term capital growth, portfolio diversification or building wealth for the future, the right strategy can give your investment decisions greater direction. This guide explains a practical six-step approach to developing and managing a property investment strategy in the UK, based on the original article’s framework.
Every effective property investment strategy should begin with a clear objective.
Before looking at properties, ask yourself what you actually want your investments to achieve. For example, one investor may want to generate monthly rental income, while another may prioritise long-term capital growth.
Start by considering your financial position and investment timeframe.
Short-term goals may include:
Medium-term objectives could involve:
Long-term goals may include:
Once you have identified your goals, put numbers against them.
Instead of saying, “I want to build a property portfolio”, you could set a target such as acquiring three investment properties within five years or reaching a specific level of annual rental income.
More importantly, your goals should be realistic and measurable. They should also be reviewed periodically because your financial circumstances, priorities and the property market can change.
Once your goals are clear, the next stage is understanding where and what you want to invest in.
Effective property investment strategies are built on research rather than assumptions. Property markets can differ significantly between regions, cities and even individual neighbourhoods.
Useful information sources include:
When researching an area, consider more than just average property prices.
Look at:
For example, an area with relatively affordable property may appear attractive because the entry cost is lower. However, if rental demand is weak, the investment may not perform as expected.
On the other hand, an area with strong employment, transport connections and growing demand may justify a higher purchase price.
The UK House Price Index can provide useful information about changes in residential property prices across different areas of the country. Investors should combine this type of data with local research rather than relying on a single source.
A property can look attractive on paper but still be unsuitable if the financial structure does not work for you.
Therefore, financial analysis should form a central part of your property investment strategy.
Begin by calculating how much capital you can realistically commit.
Consider:
Property investors may use different forms of finance depending on the property and strategy.
These can include:
Each option has different costs, eligibility requirements and risks.
For instance, a strategy that depends heavily on borrowing may produce stronger returns on the investor’s own capital when property performance is favourable. However, the same leverage can increase losses and cash-flow pressure when costs rise or income falls.
Do not focus only on the headline rental yield.
A more useful assessment considers the income remaining after relevant costs, such as:
As a result, investors should model realistic scenarios rather than relying on optimistic projections.
It can also be useful to create a spreadsheet comparing different properties under several assumptions. This allows you to see how changes in rent, interest rates, costs or property values could affect the overall investment.
With your goals, market research and finances in place, you can begin searching for suitable properties.
This is where many investors make a common mistake. They find a property they like and then try to create an investment strategy around it.
A better approach is to define your strategy first and then find properties that fit it.
For example, if your objective is rental income, you may prioritise:
Alternatively, a capital-growth strategy may place greater emphasis on:
A property evaluation checklist can include:
| Factor | What to Assess |
|---|---|
| Location | Demand, transport, amenities and employment |
| Purchase price | Value compared with similar properties |
| Rental income | Expected achievable rent |
| Condition | Refurbishment and maintenance requirements |
| Financing | Mortgage costs and borrowing requirements |
| Yield | Expected income relative to purchase price |
| Growth potential | Local development and long-term demand |
| Exit strategy | Potential resale or refinancing options |
In addition, compare several properties rather than becoming attached to the first opportunity you find.
A structured approach can make it easier to identify properties that genuinely fit your objectives.
Once you have identified a suitable property, the next stage is turning your analysis into a transaction.
This requires careful due diligence and professional support.
Depending on the transaction, your professional team may include:
Before committing to a purchase, review the relevant legal, financial and physical information.
This can include:
At this stage, do not allow enthusiasm about a potential deal to replace proper analysis.
If a survey identifies unexpected problems or the financial assumptions no longer work, reassess the opportunity before proceeding.
Purchase negotiations are not always limited to the headline price.
Depending on the circumstances, investors may also consider:
Ultimately, the objective is to complete a transaction that works financially and strategically, rather than simply securing the lowest possible purchase price.
Buying a property does not mean your work is finished.
Successful property investment strategies should evolve as circumstances change.
Set a regular review schedule and assess whether each property is still meeting its intended purpose.
Useful performance measures include:
For example, a property purchased primarily for rental income may no longer meet expectations if maintenance costs increase significantly or rental demand changes.
Similarly, a property purchased for capital growth may require a longer holding period than originally expected.
A quarterly or six-monthly review can provide a useful structure, although the appropriate frequency depends on the size and complexity of your portfolio.
During each review, ask:
By reviewing your portfolio regularly, you can identify problems earlier and make more informed decisions about retaining, refinancing, improving or selling individual properties.
The six-step framework above helps you build an investment plan, but investors can use different strategies within that framework.
Buy-to-let involves purchasing property and generating rental income from tenants.
The strategy can suit investors focused on recurring rental income and long-term ownership, although investors need to account for financing, maintenance, taxation, regulation and periods without tenants.
Houses in Multiple Occupation can generate rental income from several tenants within one property.
However, HMOs can require more active management and may involve additional licensing and regulatory requirements depending on the property and local authority.
Some investors purchase properties that require improvement and aim to increase their value through refurbishment or other changes.
The potential return needs to be weighed against renovation costs, project delays and market risk.
Property development involves creating or significantly changing property to generate a return.
Development can offer greater potential returns, but it also introduces additional risks involving planning, construction costs, financing and project management.
Commercial property can provide exposure to offices, retail, industrial, warehouse and mixed-use assets.
These investments have different lease structures and risks from residential property, so investors need to understand the specific market and asset before proceeding.
There is no single strategy that works for every investor.
The most appropriate approach depends on several factors, including:
For example, an investor with limited time may prefer a simpler buy-to-let model, while an experienced investor with more capital and time may consider refurbishment, development or HMOs.
The key is to choose a strategy that you can realistically manage.
A high projected return is not necessarily attractive if the strategy requires more capital, time or risk than you can comfortably handle.
Having a clear property investment strategy is only useful if you can find suitable properties that match it.
This is where deal sourcing can become an important part of the investment process.
Sylvest provides a platform connecting property investors with deal sourcers and property opportunities. Investors can use the platform to discover potential deals that may fit their preferred location, property type or investment approach.
The objective is not to encourage investors to purchase simply because an opportunity is available. Instead, investors can review the information provided, compare the opportunity with their own criteria and carry out appropriate due diligence before deciding whether to proceed.
For deal sourcers, the platform provides a structured way to present property opportunities to investors who may be actively looking for them.
Successful property investing starts with a strategy, not a property.
By defining clear goals, researching the UK market, analysing your finances, identifying suitable properties, completing proper due diligence and regularly reviewing your portfolio, you can create a more structured approach to property investment.
The best property investment strategies are not necessarily the most complicated. They are the ones that fit the investor’s objectives, finances, experience and ability to manage risk.
Ultimately, the goal is to make investment decisions based on evidence and clearly defined objectives rather than emotion or short-term market trends.
A property investment strategy is a structured plan for buying, financing, managing and eventually exiting property investments. It helps investors align their property decisions with their financial goals and risk tolerance.
There is no single strategy that is best for everyone. Buy-to-let, HMOs, refurbishment, development and commercial property can all suit different investors. The right choice depends on capital, experience, risk tolerance, time and investment objectives.
Start by defining your financial goals and investment timeframe. Then research the market, assess your finances, choose suitable property types and locations, establish property selection criteria and create a plan for purchasing and managing investments.
A quarterly or six-monthly review can provide a useful framework. However, investors should also reassess their strategy when there are significant changes to their finances, property portfolio, financing costs or investment objectives.
Yes. Your strategy should evolve as your financial position, experience, portfolio and market conditions change. A strategy that works for a first-time investor may not be suitable once they have built a larger portfolio.
Investors can search through estate agents, property networks, direct approaches and deal sourcers. Specialist platforms such as Sylvest can also help investors discover property opportunities presented by deal sourcers.
Building a trusted name in the UK property sector takes more than creating a platform. It requires visibility, credibility and…
Building a trusted name in the UK property sector takes more than creating a platform. It requires visibility, credibility and…
Finding a property deal is only one part of being a successful Deal Sourcer. The next challenge is finding Property…
Discover 8 essential tips for overseas property investors to make informed decisions and maximise returns on your investments.
Discover 8 essential tips for overseas property investors to make informed decisions and maximise returns on your investments.
Comments are closed here.